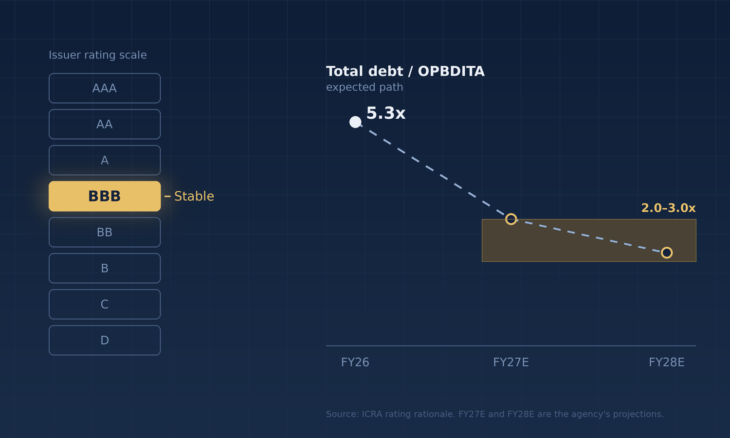
In a notable positive development, CL Educate (BSE: 540403 | NSE: CLEDUCATE), has received an [ICRA] BBB (Stable) issuer rating from ICRA Limited. The rating has also been assigned to its wholly-owned subsidiary, DEXIT Global Ltd.
This development is significant because investors had expressed concerns earlier this year regarding the company’s ability to service its debt obligations. The assignment of a BBB (Stable) rating by ICRA indicates that the company’s credit profile is considered to have moderate degree of safety regarding timely servicing of financial obligations and provides an independent assessment of its financial standing.
While the rating is not a recommendation to buy or sell the stock, it could help improve lender confidence and reduce concerns around the company’s debt-servicing capability that had weighed on investor sentiment in recent months
ICRA highlighted several factors supporting the rating, including the strong recognition of the Career Launcher brand, the group’s diversified presence across EdTech, Digital Assessment and MarTech businesses, and its experienced management team. The agency noted that CL Educate has transformed from a largely test-preparation company into a diversified education and enterprise solutions platform, reducing reliance on the traditional coaching business.
Importantly, the rating agency expects the Digital Assessment and MarTech segments to drive future growth, backed by increasing adoption of computer-based examinations, outsourcing of assessment services, digitisation of recruitment and certification processes, and expanding demand for experiential and digital marketing solutions.
While ICRA flagged the group’s leveraged capital structure, with total debt-to-OPBDITA at 5.3x as of March 2026, it maintained a Stable outlook, reflecting its expectation of steady revenue growth, improving earnings and gradual strengthening of credit metrics.
A key statement in the credit rating rational by ICRA says: With the scheduled repayment of acquisition debt and expected growth in earnings, the company’s leverage and debt coverage indicators are projected to improve over the medium term. total debt/OPBDITA is expected to be 2.0-3.0 times and DSCR 1.0-1.5 times over FY2027 and FY2028. Total debt as on 31st March 2026 was ~Rs 232 crore, while TTM OPBITDA after Q1 FY27 results was Rs 48 crore. The expected fall in total debt/OPBDITA to fall towards 2x by FY28 budgets in growth in OPBITDA and reduction in total debt.
For investors, the rating provides an independent assessment of CL Educate’s business position and liquidity profile. More importantly, it addresses a key overhang that had impacted sentiment: concerns around the company’s ability to service acquisition-related debt.
Disclosure: Wisdom-IR is investor relations advisor to CL Educate. In case you have any queries for the management, you can address them to us.
#CLEducate #CareerLauncher #DEXITGlobal #ICRA #creditrating